DeFi yield fees vs emissions is the first distinction to make before treating an advertised APY as economic return. Two pools can both display 20%, yet one may be funded by users paying to trade or borrow while the other distributes newly issued tokens to attract temporary liquidity.
The percentage alone does not reveal the difference. Dashboards may combine trading fees, interest, token rewards, points and leveraged exposure into one headline figure even though each component has a different payer, risk and expiration condition.
This article builds a repeatable source-of-yield test and applies it to one live position: the USDC/AERO pool on Aerodrome V1 on Base. The snapshot is dated September 29, 2026 because reward rates, token prices, TVL and weekly allocations can change quickly. It is a methodology case study, not a forecast or recommendation.
DeFi Yield Fees vs Emissions: The Economic Difference
Yield from fees begins with an external economic action. A trader pays a swap fee, a borrower pays interest, a user pays for blockspace or a protocol earns revenue from a service. Part of that payment is then allocated to the capital provider.
Yield from emissions begins with a token-distribution rule. A protocol releases governance or incentive tokens and allocates them to users who supply liquidity, lend, stake or vote. The reward can have market value, but it does not require an equivalent amount of current customer revenue.
| Yield component | Immediate payer | What sustains it | Main failure mode |
|---|---|---|---|
| Trading fees | Traders | Persistent volume and fee capture | Volume or active liquidity falls |
| Borrow interest | Borrowers | Utilization and solvent borrowing demand | Demand falls or bad debt appears |
| Token emissions | Protocol token schedule or treasury | Continued allocation and reward-token value | Emissions are reduced or the token price falls |
| Points | No guaranteed current payer | Expectation of a future benefit | No conversion, dilution or changing rules |
| Leveraged carry | Spread between earned and borrowed rates | Positive net spread and stable collateral | Borrow cost, liquidation or deleveraging |
Organic DeFi yield is often used as shorthand for returns supported by real protocol use. That term should still be defined carefully. Fees may be real while temporary, wash-driven or too small to compensate liquidity-provider losses. “Fee-funded” describes the source; it does not automatically mean sustainable or low-risk.
Why One Headline APY Can Hide Several Products
APY annualizes a return and normally assumes some form of compounding. APR annualizes without the same compounding assumption. A dashboard can convert several volatile daily or weekly inputs into an annual number that looks precise even when the underlying rate changes every epoch.
The headline may also depend on a specific action. An unstaked liquidity position may receive swap fees, while the same LP token staked in a gauge may surrender those fees and receive emissions instead. A vault can then auto-compound the rewards, and a leveraged product can borrow against the position to display a still higher return.
This is why BlockCodex’s guide to evaluating DeFi platforms for passive income starts with the source of yield rather than the size of the percentage. The product name is not enough; the exact deposit route matters.
A Four-Layer Source-of-Yield Test
Every advertised return can be decomposed into four layers. The categories should be kept separate even when the interface combines them.
Layer 1: fees or interest paid by users
Identify the transaction that creates the return. For a DEX pool, record the swap-fee rate, eligible volume, active liquidity and the share actually assigned to the depositor. For lending, identify borrower interest, utilization and the reserve factor.
The relevant question is not whether the protocol generates fees somewhere. It is whether the specific position receives those fees.
Layer 2: token emission rewards
Record the reward token, units distributed per period, token price, duration and allocation rule. Token emission rewards are economically exposed to two variables at once: the number of tokens distributed and the market value of each token.
A 20% reward APR can fall even if the protocol changes nothing. If the reward token loses half its value while deposit TVL and token distribution remain constant, the dollar-denominated reward rate approximately halves.
Layer 3: points or expected future rewards
Points should not be converted into APY unless a documented conversion rate, supply and redemption mechanism exist. A ranking, multiplier or eligibility score may have speculative value, but it is not current cash flow.
Report points separately as an unpriced contingent benefit. If no official points program can be confirmed for the exact position, mark it “not evidenced” instead of inserting a zero-dollar estimate that looks more certain than the available documentation.
Layer 4: leverage and repeated capital
Check whether the strategy borrows, loops collateral or rehypothecates an LP token. Leveraged APY is not a new yield source; it magnifies the spread between existing yield and financing cost while adding liquidation, interest-rate and exit risk.
For an unleveraged deposit, use a 1.0× exposure multiplier. For a looped strategy, publish gross assets, debt, net equity, borrow APY and liquidation conditions rather than only the boosted return.
Live Case Study: Aerodrome USDC/AERO
Aerodrome is a decentralized exchange on Base with basic and concentrated liquidity pools. Its official liquidity documentation explains that pool fee APRs use accrued swap fees and that staking APR calculations depend on the liquidity eligible for rewards.
The protocol’s incentive design separates the recipients of fees and emissions. Aerodrome’s contract specification states that LP depositors who place LP tokens in a gauge relinquish the associated fees; those fees become voting rewards, while the gauge distributes AERO emissions to staked LPs.
That distinction makes the USDC/AERO pool useful for this test. A protocol can produce genuine swap fees while the yield displayed for the staked LP position remains reward-driven.
Snapshot and observed decomposition
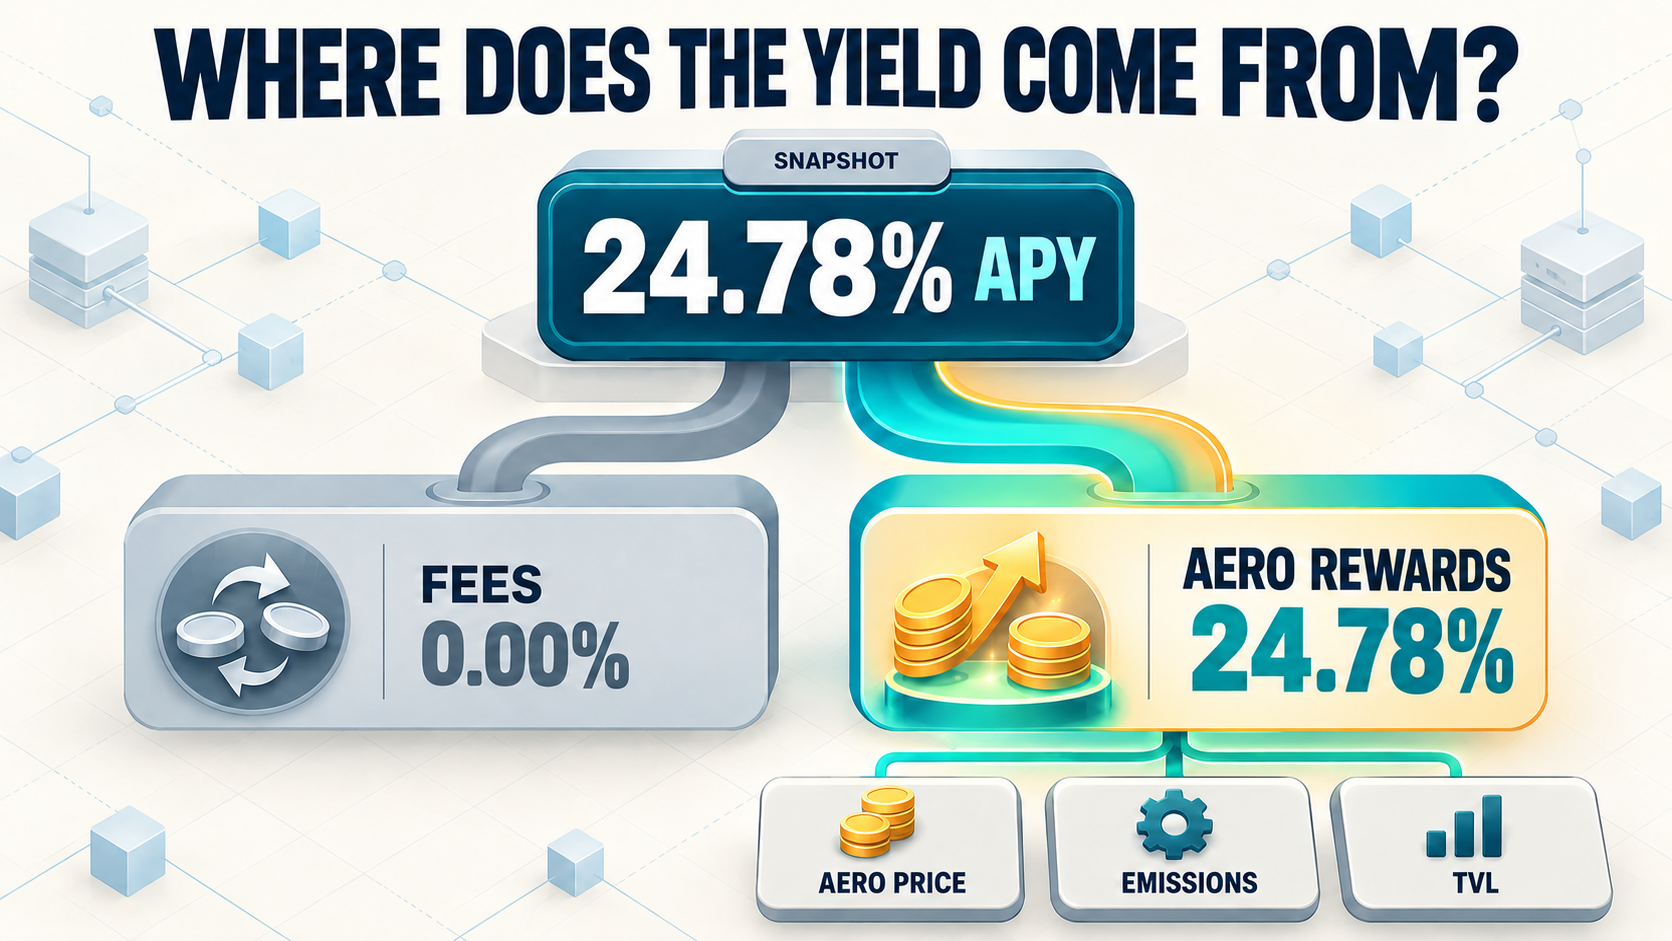
During the September 29, 2026 review, DeFiLlama’s Aerodrome market view displayed the basic volatile USDC/AERO pool with approximately $41.32 million in TVL and 24.78% APY. Its breakdown showed the same 24.78 percentage points as AERO rewards, with no separate base-yield contribution displayed.
An earlier capture of the individual pool page showed 28.80% reward APY and $36.27 million of TVL. Across the two public captures, the displayed rate fell 4.02 percentage points while TVL increased by about $5.05 million. The pages can refresh at different times, and the comparison cannot prove that TVL alone caused the change; it demonstrates why every live yield claim needs a timestamp and source surface.
| Observed field | Snapshot value | Classification |
|---|---|---|
| Protocol and chain | Aerodrome V1 on Base | DEX liquidity position |
| Pool | USDC/AERO basic volatile AMM | Two-asset LP exposure |
| TVL | Approximately $41.32 million | Denominator affecting reward rate |
| Displayed total APY | 24.78% | Headline yield |
| Displayed reward component | +24.78 percentage points in AERO | Token emissions |
| Displayed base component | No separate base yield displayed | 0% in this rounded dashboard decomposition |
| Points | No official pool-specific points benefit confirmed in the reviewed sources | Not evidenced |
| Leverage | None in the direct LP-and-stake position | 1.0× before any external borrowing strategy |
The arithmetic is simple:
Displayed total APY = displayed base component + displayed reward component
24.78% = 0.00% + 24.78%
Using the rounded values displayed by the data provider, the reward share was therefore:
24.78 ÷ 24.78 = 100%
This does not mean the pool generated no swap fees. It means the selected staked-position yield was represented as AERO rewards rather than fee yield in the observed decomposition. The protocol’s own design explains why protocol fees and depositor yield can belong to different recipients.
Original DeFi Yield Sustainability Stress Test
A live APY is a snapshot, not a promise. To test DeFi yield sustainability, the reward component can be stressed independently while holding all unmentioned variables constant. The calculations below are controlled scenarios, not predictions.
| Scenario | Controlled assumption | Approximate reward APY | Change from snapshot |
|---|---|---|---|
| Snapshot | Observed reward price, emissions and TVL | 24.78% | Baseline |
| Reward-token price shock | AERO price falls 50%; token units and TVL unchanged | 12.39% | -12.39 percentage points |
| Emission reduction | AERO units allocated to the pool fall 40%; price and TVL unchanged | 14.87% | -9.91 percentage points |
| Combined shock | AERO price falls 50% and allocated token units fall 40% | 7.43% | -17.35 percentage points |
| Liquidity inflow | Eligible TVL doubles; reward value is unchanged | 12.39% | -12.39 percentage points |
The model uses proportional approximations. Reward APY scales with the dollar value of tokens distributed and inversely with eligible capital when everything else is fixed. Real outcomes can differ because price, emissions, TVL, compounding frequency, liquidity range and voter allocations can change together.
For a hypothetical $10,000 position, 24.78% corresponds to $2,478 of annualized reward value only if the displayed rate, AERO price, allocation and eligibility remained unchanged for a year. Under the combined controlled shock, the annualized value falls to approximately $743. This comparison demonstrates sensitivity; it is not a forecast of cash received.
Why Protocol Fees Do Not Automatically Make LP Yield Organic
A common analytical shortcut compares total protocol fees with total token emissions and then labels every depositor return sustainable or unsustainable. That approach ignores distribution rights.
In Aerodrome’s design, staked LPs receive emissions, while fees relinquished by gauge depositors accrue to the voters supporting the pool. A protocol-level fee can therefore be economically real without funding the staked LP’s advertised APY.
Three separate questions are required:
- Does the protocol generate fees?
- Who receives those fees?
- What specifically funds the return shown for this position?
The first question measures product demand. The second measures value distribution. The third identifies depositor economics. Only the third can classify the advertised yield.
How to Audit Yield Farming Incentives Before Depositing
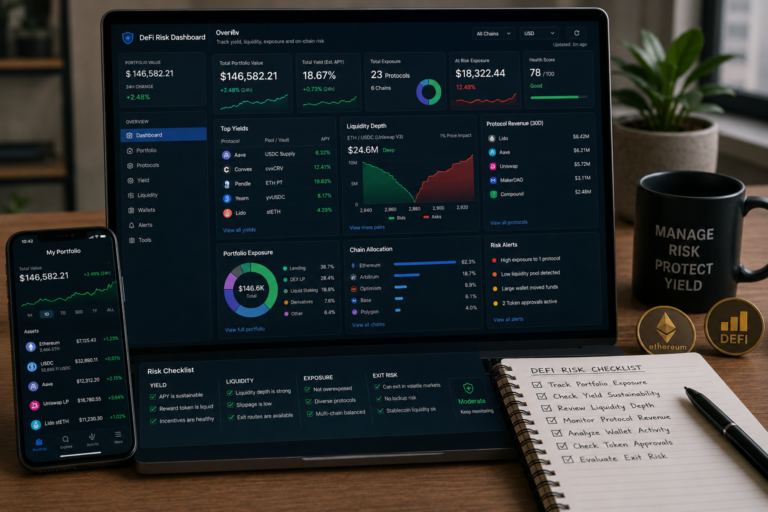
A repeatable audit should produce a small source ledger rather than a general impression. BlockCodex’s comparison of DeFi risk tools can help locate the relevant dashboards, but every figure still needs to be matched to protocol documentation and the exact position.
- Freeze the snapshot. Record the protocol, chain, pool, timestamp, TVL, displayed APY and the page or API used.
- Name the position state. Separate unstaked LP, gauge-staked LP, vault receipt and leveraged strategy.
- Identify the payer. Trace fees to traders, interest to borrowers and emissions to a token schedule or treasury.
- Split the headline rate. Report base yield, reward yield, unpriced points and leverage separately.
- Check the reward asset. Record its price source, liquidity, issuance schedule and claim conditions.
- Check duration. Determine whether rewards renew weekly, end on a fixed date or depend on governance votes.
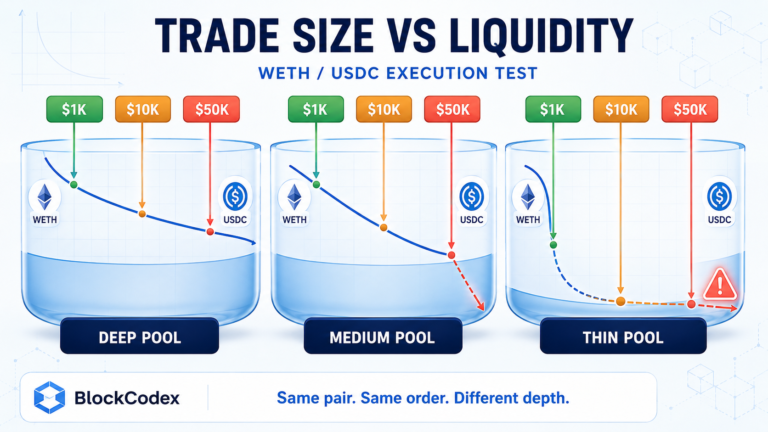
- Stress the denominator. Model what happens when TVL rises, because the same reward budget must be shared by more capital.
- Check the exit. Measure pool depth, range exposure, slippage and the route for converting reward tokens.
Yield farming incentives can be useful for launching liquidity, but their purpose is acquisition. They should not be treated as permanent protocol earnings unless the mechanism and funding source support that conclusion.
Questions That Reveal the Real Yield Source
| Question | Evidence to inspect | Warning sign |
|---|---|---|
| Who pays the return? | Swap fees, borrower interest, reward contracts, treasury transfers | No identifiable economic payer |
| Which asset is paid? | Underlying asset or reward token | Return depends on a thinly traded token |
| How long does it last? | Epoch, governance vote, campaign end date | Annualized rate from a short incentive window |
| Who receives protocol fees? | LP, voter, token locker, treasury or buyback contract | Protocol fees exist but bypass the depositor |
| Are points included? | Official terms and conversion rules | Undocumented future value counted as current APY |
| Is leverage present? | Debt, collateral loop, liquidation threshold | Borrow costs or liquidation omitted from headline yield |
| Can the position exit? | Depth, slippage, active range and reward-token liquidity | High APY paired with weak exit liquidity |
Exit analysis belongs in the yield calculation because a reward has limited economic value if it cannot be converted efficiently. BlockCodex’s article on DeFi liquidity risk explains why TVL, active range and stress liquidity should be reviewed separately from the displayed return.
What This Case Study Cannot Prove
The snapshot does not prove what the USDC/AERO pool will earn over the next day, epoch or year. The displayed APY can change with AERO price, voter allocations, eligible liquidity, pool activity and the data provider’s methodology. The 24.78% and 28.80% public captures observed during this review show that even two recent surfaces can contain different time slices.
The 100% reward share is based on the rounded decomposition visible in the selected snapshot. It should not be interpreted as a claim that the pool produced exactly zero fees or that no LP configuration can receive fees. Aerodrome distinguishes staked and unstaked positions, so product state changes the recipient.
I could not confirm an official points conversion or separate pool-specific points benefit for this direct position in the reviewed Aerodrome documentation. The analysis therefore marks points as “not evidenced,” not as permanently impossible.
The stress scenarios also exclude impermanent loss, gas costs, compounding costs, range management and tax. Those items affect net return but do not change the first analytical task: identifying the source of the advertised yield.
Final Takeaway on DeFi Yield Fees vs Emissions
DeFi yield fees vs emissions cannot be resolved by checking whether a protocol generates revenue somewhere. The analyst must trace which cash flow reaches the exact position being advertised.
In the September 29 snapshot, the Aerodrome USDC/AERO position displayed 24.78% APY and attributed the same 24.78 percentage points to AERO rewards. The protocol can still generate genuine swap fees, but its documented distribution rules direct the relevant fees from staked liquidity toward voters while gauge-staked LPs receive emissions.
The result is a clear classification: the observed advertised yield was emission-funded in the rounded dashboard breakdown, with no confirmed points benefit and no leverage in the direct position. Its sustainability therefore depends primarily on the AERO reward allocation, AERO’s market value and the amount of eligible liquidity sharing those rewards.
A credible yield review should always show the payer, asset, duration, recipient, denominator and exit route. Once those six fields are visible, a headline APY becomes an economic mechanism that can be tested rather than a percentage that must be trusted.
Frequently Asked Questions
What is the difference between fee yield and emission yield?
Fee yield is funded by economic activity such as swaps or borrowing. Emission yield is funded by distributing tokens according to a protocol incentive schedule. Both can have value, but they depend on different sources and fail under different conditions.
Does fee-funded yield mean a DeFi position is safe?
No. Fee-funded yield can still be volatile, insufficient or outweighed by impermanent loss, smart-contract exposure and exit costs. It identifies the payer; it does not remove risk.
Why can token reward APY fall without an emission cut?
The displayed reward is usually valued in dollars. If the reward-token price falls or more capital shares the same token allocation, the APY can decline even when the number of tokens distributed does not change.
Should DeFi points be included in APY?
Only when an official and enforceable conversion mechanism establishes their value. Otherwise, points should be reported separately as an unpriced contingent benefit.
Can a protocol generate fees while an LP earns only emissions?
Yes. Fee generation and fee distribution are separate questions. Aerodrome’s documented gauge design is an example: fees associated with staked LP liquidity can accrue to voters while staked LPs receive AERO emissions.
Sources and Methodology
The case study uses Aerodrome’s official liquidity documentation and contract specification to identify pool, staking, fee and reward mechanics. The live pool values were recorded from DeFiLlama’s AERO market and yield view on September 29, 2026. The controlled scenarios change one or two variables at a time and assume all other inputs remain constant. Recheck every live number immediately before publication because weekly epochs, token prices and eligible TVL can change the displayed result.